6 Apr 2027
Most unused pension funds and death benefits are expected to enter the estate for IHT.
Watch our video to get to know Oculus and to understand the overarching changes. Then complete the IHT Pension Checklist with focused prompts for families whose estate includes valuable homes, additional property or property-owning interests.
Educational information, not personal advice. Tax rules can change and individual circumstances vary. FCA Number: 1002893
Why property changes the conversation
Most unused pension funds and death benefits are expected to enter the estate for IHT.
The estate level at which the residence nil-rate band begins to taper away.
The standard IHT rate on value above the allowances available to the estate.
Source: HMRC technical note on Inheritance Tax and pensions.
Your working guide
This guide is for information only and does not constitute personal financial advice. The Financial Conduct Authority does not regulate taxation advice.
Part One
Build one view of the assets that may form part of your estate. These prompts are a starting point, not a tax calculation.
Part Two
Bring the right information together before discussing whether any changes are suitable for you.
Part Three
Family circumstances and ownership structures can materially change the position. Flag these points for tailored advice.
Questions
The announced change concerns unused pension funds and death benefits, not a new tax specifically on homes. Property already forms part of many estates, so adding pensions may increase the total value exposed to IHT.
Not necessarily. The outcome depends on the whole estate, liabilities, available exemptions and allowances, who inherits, and individual circumstances.
It may be available when a qualifying residence passes to direct descendants, subject to conditions. It begins to taper for estates above £2 million.
No. Most unused pension funds and death benefits are in scope, but death in service benefits from registered schemes and certain dependant scheme pensions are excluded.
No. It is educational information. Tax treatment depends on individual circumstances and may change, so take personalised advice before acting.
Your adviser
Oculus Wealth Management (Westminster) provides financial planning and wealth management to private clients and their families, including joined-up retirement and estate planning.
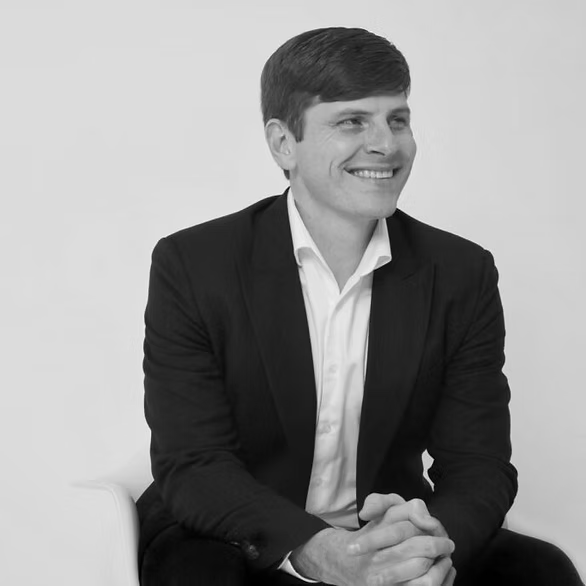
Charles has been a Chartered Financial Planner and Fellow of the Personal Finance Society since 2014.
He specialises in estate planning, retirement solutions and tax-efficient investment planning.
Charles delivers holistic advice alongside discretionary fund managers, accountants and solicitors.
Oculus Wealth Management is a trading style of Oculus Wealth Management (Westminster) Ltd which is an appointed representative of Oculus Wealth Management Ltd, 2 Grove Park Court, Harrogate, HG1 4DP, a company authorised and regulated by the Financial Conduct Authority. Company number 15140318
Your next step
An Oculus adviser can review your pensions and wider estate, explain where the 2027 rules may affect you, and help you decide whether any action is appropriate.
A conversation does not commit you to making changes.